

As the Federal Reserve takes an extra long pause between its July and September policy meetings, as it does every year due to the way its calendar of eight meetings is structured, the latest jobs report has thrown a bit of a monkey wrench into bets made on a Fed rate hike at its next meeting. Inflation is still well above its 2% target but the July employment report has just come in weaker than expected with a loss of 23,000 workers - even as the unemployment rate fell- and all of this on the heels of a very weak June monthly inflation report. What’s a central bank to do?
Enter Mickey Levy. He has been following the Federal Reserve and its policy twists and turns through many businees cycles from his work as a Wall Street economist to his research at Stanford’s Hoover Institution, and as a longtime Shadow Open Market Committee member. Mickey sees an economy that is on a solid growth path, and a Kevin Warsh led Fed that will come around sometime by the end of the year to the need to hike interest rates.
“The economy is still very healthy and resilient. Every indicator suggests that the economy is growing, the probability of recession very, very low, and the economy has been very effective and efficient in responding to some nasty negative supply shocks,” he says. “Don’t put too much focus on any single number.”
Levy highlights the divergence between private and public sector employment, noting, “Private sector employment was up 30,000. It was offset by a one time 50,000 decline in employment at the local government level for education. So the economy is still resilient.” This suggests that the headline employment numbers may mask underlying sectoral differences, and that the private sector continues to show strength even as public sector jobs fluctuate.
A key concern for Levy is the declining labor force participation rate. “Probably the most interesting aspect of the employment report that came out was the continued decline <in> the labor force participation rates, the labor force itself and the employment-to-population ratios,” he says. And it’s “quite interesting that people, for a variety of reasons, are deciding to drop out of the labor force and move away from jobs at a time when businesses have been very efficient in managing their labor inputs to production.”
Levy also points to a mismatch between labor supply and demand, as “businesses have argued that there’s not enough labor supply out there with appropriate skills. So this is a very interesting issue that is worth monitoring beyond the normal volatility in the headline employment number.”
Mickey highlights the paradox of strong productivity gains alongside falling real wages. “That type of increase in average hourly earnings is suggesting that wages are declining in inflation adjusted terms…is really unsustainable. And it’s seemingly inconsistent with the strong gains in labor productivity.”
He attributes much of the economy’s growth potential to productivity, especially in the context of slower labor force growth due to immigration policy: “If you look at sustainable potential growth in the economy, about 75% - 80% of it is driven by productivity. And the other part is labor force growth... the biggest mover here is productivity gains that have continued to outpace forecasts by, say, the Federal Reserve and the Congressional Budget Office.”
He warns that both markets and policymakers can be too reactive to headline numbers like July drop in jobs. “How much emphasis will the Fed put on one single number? Will it be just as fickle as financial markets in changing the response to one number?”
Mickey believes that the FOMC, under Kevin Warsh’s leadership, should avoid the pattern of responding more aggressively to labor market weakness than to above-target inflation. “That is consistent with the Fed’s history that it always responds much more quickly and aggressively to weak labor markets than it does to undesired higher inflation. So the big question now is will Warsh back up this new regime…”He's talking about this, this, legacy that he wants of getting inflation to 2%. I think he will.”
So dive in and hear why Mickey expects Warsh to lead the FOMC in that direction, albeit slowly. “I cut Warsh some slack meaning you don't have to achieve it the moment you come into office… He's created these outside task forces that I think could have very positive influences on the Fed's way of thinking. I'm an optimist there and give it time.
“And I think eventually the Fed is going to say, yeah, monetary policy is still a little on the accommodative side. We will probably need to hike rates.”
A spotty report but still a resilient economy 00:01:14:09
The economy is still very healthy and resilient. Every indicator suggests that the economy is growing, the probability of recession very, very low, and the economy has been very effective and efficient in responding to some nasty negative supply shocks. Don’t put too much focus on any single number. Kathleen. We had six months in 2025 where employment net net was down, and it declined in more than half of those months.
Private jobs grew local government shrank 00:01:51:22 -
And in in the report that came out today for July, private sector employment was up 30,000. It was offset by a one time 50,000 decline in employment at in at the local government level for education. So the economy still resilient. And, of course, one of the big issues going forward is. How much emphasis will the fed put on one single number? Will it be just as fickle as financial markets and changing the response to one number?
Participation rates are dropping 00:03:16:22
Most of the markets and media focus on that headline establishment payroll number. Probably the most interesting aspect of the employment report that came out was the continued decline and the labor force participation rates, the labor force itself and the employment to population ratios. And those are those are quite interesting that people, for a variety of reasons, are deciding to drop out of the labor force and move away from jobs at a time where businesses have been very efficient in managing their labor inputs to production.
But businesses complain about qualified supply of labor! 00:04:12:01
And businesses have argued that there’s not enough labor supply out there with appropriate skills. So this is the this is a very interesting issue that is worth monitoring beyond the normal volatility in the headline employment number.
Real wages are falling! 00:05:19:13
Well this is this is a very interesting issue, particularly in the context of the higher inflation we’ve had recently, that type of increase in average hourly earnings is suggesting that wages are declining in inflation adjusted terms. And that is.
Unsustainable, inconsistent, but happening? 00:05:43:04
Really unsustainable. And it’s seemingly inconsistent with the strong gains in labor productivity. And so that’s worth keeping an eye on. But once again, when we look at labor markets from a broader perspective, businesses are still in this low hiring, low firing mode. They’re very efficient in using labor inputs. But at the same time, they and labor markets have been thrown a nasty curveball.
Closed borders require special analysis 00:06:26:22
With President Trump’s clampdown on immigration policy. These are all issues that affect economic growth and the efficiency of the economy. From the Fed’s perspective, it has to digest these and think about its broader objectives of its dual mandate.
Productivity is in the driver’s seat 00:07:17:17
If you look at hours worked year-over-year, there are up 0.8%. But if you look from the broader perspective, productivity gains have been very healthy. And if you look at sustainable potential growth in the economy, about 75% - 80% of it is driven by productivity. And the other part is labor force growth. That is growth in aggregate employment and aggregate hours worked. And so the biggest mover here is productivity gains that have continued to outpace forecasts by, say, the Federal Reserve and the Congressional Budget Office. So productivity has been growing very nicely. And this is one of the biggest issues facing the economy and financial markets. And that is will the implementation and build out of AI continue to add to productivity being above trend. And that’s particularly important in light of the clampdown on immigration that has slowed labor force growth.
Broader view or labor compensation is less dire 00:09:11:18
Well, if you look at a broader perspective beyond aggregate average hourly earnings, if you look at total compensation to workers wages and salaries, plus, you know, pension contributions by companies, it is growing at a pretty healthy clip and above inflation. So if you look at the at the whole package. Workers are doing okay. And once again the overall economy is very healthy, has been surprisingly resilient. And once again, from the broadest perspective, when I look at the Fed’s dual mandate, it has really met the its employment objectives, but it is not met its inflation target.
Productivity- nothing officially but anecdotally seems important 00:11:09:15
So it’s really too early to say empirically with any certainty that AI is contributing to the stronger productivity gains. We need more years of data. Anecdotally, I would say definitively yes, AI is boosting efficiencies at corporations and increasing worker productivity. If it doesn’t show up in the broader measure of productivity, that is that is, you know, that is published by the government.
Different ways to look at it 00:11:55:02
That is, if you look at the government’s official measure of productivity, it takes private sector output, that is GDP minus government purchases and divides it by aggregate hours work. Okay, now that makes sense. But corporations have different metrics for productivity and efficiency.
AI is probably a productivity plus 00:12:25:18
And one of the key differences here is so many of US based corporations have overseas activities and overseas production that don’t even show up in GDP because GDP measures domestic production, but it certainly shows up on their balance sheets and in their profits and returns to capital. So you’ve got to think through this, pretty carefully. But my strong hunch is that AI is a definitive positive okay.
...and probably not reducing jobs! 00:13:12:02
And it is not reducing jobs okay. It is generating churn in labor markets where some jobs are lost, but others are created. And just like other technological innovations in history, this one will end up creating net new jobs.
ISM services pointed to weaker service sector growth 00:14:18:24
The ISM report on service providers. And did register a decline in the employment index in services. But that’s a one-month number. Okay. Keep in mind these monthly numbers bounce around a lot. They’re seasonally adjusted. I like the overall ISM surveys because they tend to be a pretty reliable indicators overall of the economy.
ISM headlines for manufacturing and services show expansion 00:14:55:21
And if you look at the composite ISMs or you look at the manufacturing and services separately, they’re both well into the expansion zone. So it’s consistent with my view that the economy is growing and resilient. And once again, Kathleen, the employment report for July was weak. But don’t overstate one month of weakness.
Weak household survey...an ongoing anomaly? 00:16:04:06
Yeah. In the last couple of years, we have seen a net decline in employment in the household survey. You’ve also seen in the household survey a decline in the labor force and the labor force participation rate in the establishment survey. That is the survey of businesses. Payroll employment continues to grow year-over-year at a very modest pace, but it is clear the rate of growth is clearly flattened out in the last couple of years relative to its pace of growth, say in the decade before the, the pandemic.
Businesses are using labor very efficiently 00:16:50:01
So but you know, once again, I would say standing back and looking at the economy, businesses have been very efficient in using labor. There’s sufficient labor, there’s sufficient demand for labor. We see that in the JOLTS report. And once again, I the fact that you’re asking me so many questions about labor markets just after this July lousy July employment number came out, you know, puts focus on this critical question how much weight will the Fed put on it and will the number what will happen to to the August number which comes out, you know, early on.
Achieving half of the duel mandate 00:19:18:22
Okay. I think the broader context is and the Fed acknowledges this is the economy has been resilient. Employment as basically achieved the Fed’s employment mandate. But inflation is obviously decidedly above the Fed’s 2% target. So one of the first questions to consider is monetary policy. What is its current stance. And you know, up until this last meeting is Chair Jay Powell argued that monetary policy was slightly restrictive… and a different measures suggest, no… that monetary policies actually a bit accommodative.
Different strokes for different folks 00:20:12:04
That is, if you look at the 6.5% growth in in nominal GDP, which is, you know, the broadest measure of aggregate demand in the economy is too rapid. If you look at the real funds rate, which is negative compared to the headline PC price index, if you look at it compared to core PC, it’s barely in the positive zone and below the Fed’s 1% estimate of the longer run.
Is it really a new regime? 00:20:42:04
R-star… even if you looked at a Taylor rule, a Taylor rule estimate would be closer to four and a half now. And so all of these measures suggest that the monetary policy is accommodative. And so Kevin Warsh comes in and he says, look, there’s a new regime at the fed. And what does that mean? And I think one interpretation is Powell allowed above 2% inflation. He paid ‘lip service’ to getting inflation back to 2%. But just look at 2025 when the Fed lowered rates even though inflation was above 2%. That is consistent with the Fed’s history that it always responds much more quickly and aggressively to weak labor markets than it does to undesired higher inflation. So the big question now is will Warsh back up this new regime.
An eventual need to hike rates 00:21:49:16
He’s talking about this, this, legacy that he wants of getting inflation to 2%. I think he will. But I cut Warsh some slack meaning you don’t have to achieve it the moment you come into office. He’s created a debate. He’s created these outside. Task forces that I think could have very positive influences on the Fed’s way of thinking. I’m an optimist there and give it time. So the Fed has to have to think through these issues. And I think eventually the Fed is going to say, yeah, monetary policy still a little on the accommodative side. We will probably need to hike rates.
What’s next? 00:22:44:22
But once again we could come back to today’s context and say Will the Fed over respond to one weak employment number? And what will the August data tell us before the Fed meeting? These are all very interesting issues.
Higher oil prices have been a hurdle but not insurmountable 00:23:47:11
Okay. So of course the higher oil prices have been a distinct negative. They have pushed up headline inflation. However, to your point, looking at the core PCE inflation data and the CPI data, the pass through of the higher energy prices to core measures of inflation have been very modest. And that’s a good sign. In addition, looking at measures of inflationary expectations, the higher oil prices haven’t really driven up market-based expectations of measures of inflationary expectations. So far so good. And you know I’m hoping that all prices you know come down a little lower. And but once again the pass through to core inflation has not been that large. And the Fed like all of us has, has to think about it as kind of a undesired curve ball.
Fed policy still accommodative, rate hikes will be needed 00:25:23:22 - 00:25:47:02
I’d say… when I look at the different measures of monetary thrust, monetary policy still accommodative. And I would like to see the fed move toward hiking rates. I don’t think it’s going to take aggressive hiking. But Kathleen, let’s put it into context.
Inappropriate rate cuts & inflation tolerance 00:25:47:04
Last year, the Fed cut rates three times at the last three meetings. Okay. That was in response to weak labor markets. And we heard at the time some Fed members saying, oh, we have to get used to some negative numbers. So they responded very quickly. Employment turned around and bounced back quickly. Those three rate ,Cuts> were inappropriate. They reflected how the Fed always responds more quickly to labor market weakness than to inflation. And they also showed that under the Powell regime, the Fed was willing to put up with higher inflation.The Fed may have to take those away. But let’s let’s see… let’s see, okay?
Task forces- a good idea 00:27:20:16
I think the task forces are a really good idea. There are some stellar people sharing those task forces. They could bring new ideas and new thoughts, and they could lead the Fed staffers to think about issues in, in different and constructive ways. Let’s take, for example, inflation. The Fed’s big macro model could use a lot of help in its ability to understand and forecast inflation.
Task forces: An end run around insularity 00:28:02:21
Just simple ideas could help on not just forecasting inflation, but on communications and some of the other topics. And it’s very it’s very easy for a big, powerful organization like the fed to become too insular and not open to new ideas. And I’m hoping that that the task forces lead to new and fresh thinking. And so I applaud their creation, and I hope they’re successful. And I don’t think you need to put any time deadline on them. I just think it’s it’s very valuable to use them as, as sounding boards and to bring out new ideas. I like it okay.
Credibly staffed task forces should be heard 00:29:29:15
Kathleen, let me let me follow up on what that the framework review, particularly the one conducted in 2019, was all set in stone on what the Fed wanted to achieve. It was preordained. What they were going to come out and recommend. Ditto in 2025. It was all built in and in the cards it did not involve any new creative thinking, just regurgitating the old thought processes and the old models. And those are the ones that need to be challenged. And some of these task force leaders are absolutely stellar thinkers, and it would behoove the Fed to, you know, listen to what they say and take seriously and have an interesting discussion about them.
A farewell to Mickey 00:30:57:06
Thanks for having me, Kathleen.
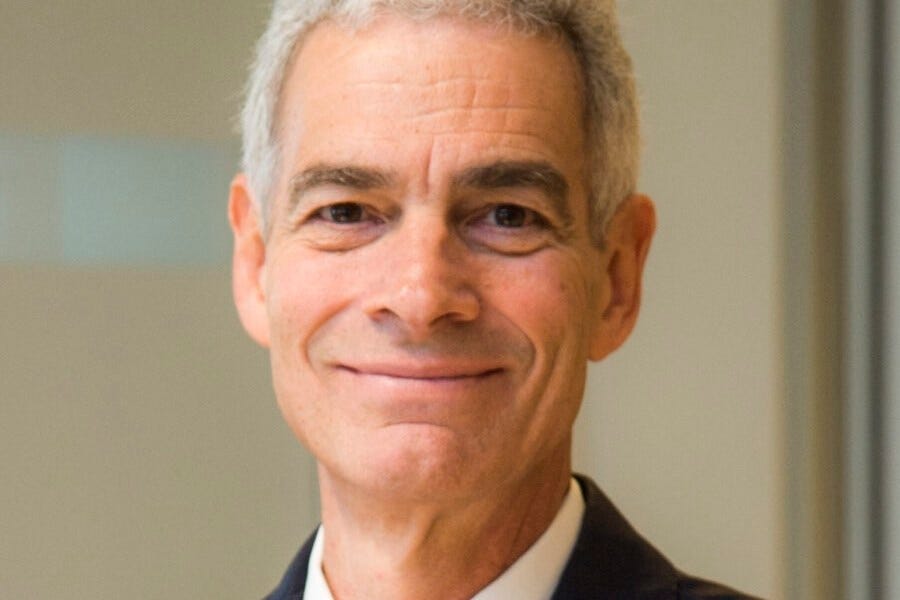
Dr. Mickey D. Levy
Mickey Levy is a macroeconomist who uniquely analyzes economic and financial market performance and how they are affected by monetary and fiscal policies. Dr. Levy started his career conducting research at the Congressional Budget Office and American Enterprise Institute, and for many years was Chief Economist at Bank of America, followed by Berenberg Capital Markets. He is a Visiting Fellow at the Hoover Institution at Stanford University and a long-standing member of the Shadow Open Market Committee. He is a member of the Council on Foreign Relations.
Dr. Levy is a leading expert on the Federal Reserve’s monetary policy, with a deep understanding of fiscal policy and how they interact. He has researched and spoken extensively on financial market behavior, and has a strong track record in forecasting. Dr. Levy’s early research was on the Fed’s debt monetization and different aspects of the government’s public finances. He has written hundreds of articles and papers for leading economic journals on U.S. and global economic conditions, and has been an active voice on how financial markets are influenced by monetary policy. He has testified frequently before the U.S. Congress on monetary and fiscal policies, banking and credit conditions, regulations, and global trade, and is a frequent contributor to the Wall Street Journal, Bloomberg, and other media.
Dr. Levy holds a Ph.D. in Economics from University of Maryland, a Master’s in Public Policy from U.C. Berkeley, and a B.A. in Economics from U.C. Santa Barbara.


